The Stablecoin Debit Card Revolution: Why It’s Not Just About Payments
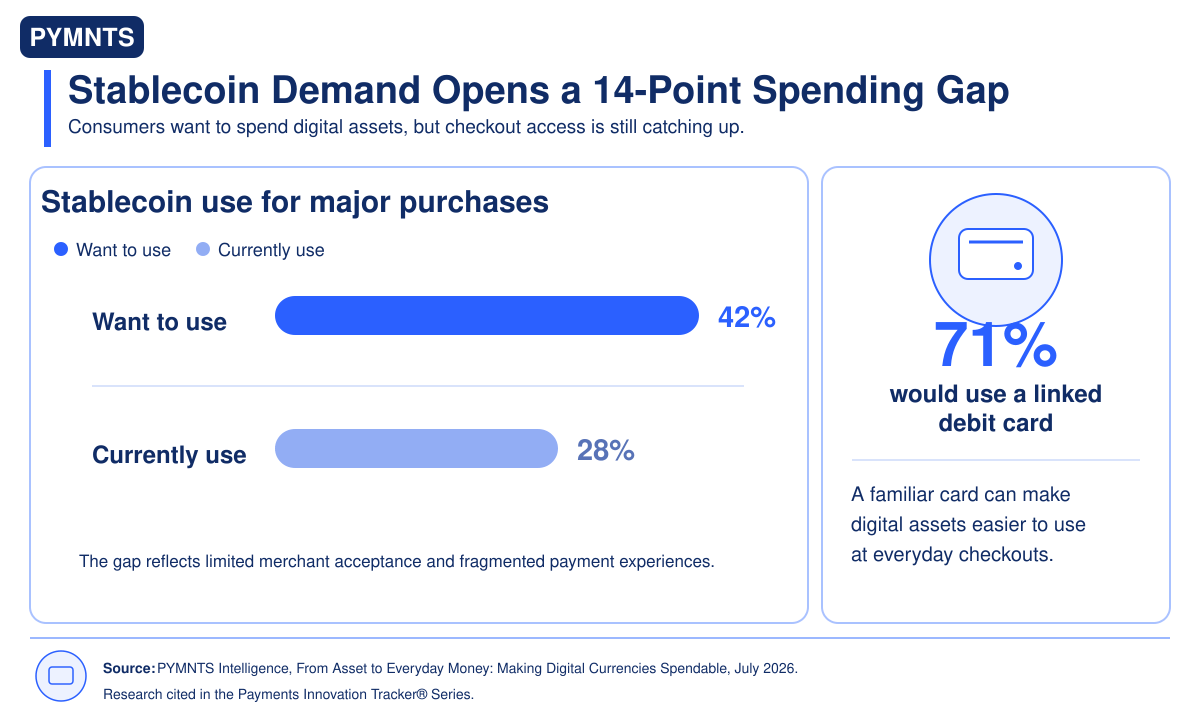
There’s a quiet revolution brewing in the world of digital assets, and it’s not about another token launch or a new blockchain protocol. It’s about something far more mundane—yet profoundly transformative: the humble debit card. A recent report from PYMNTS Intelligence reveals that 71% of stablecoin holders would spend their digital assets if they could link them to a debit card. On the surface, this sounds like a simple convenience. But if you take a step back and think about it, this statistic is a seismic shift in how we perceive digital currencies.
The Familiarity Factor: Why Debit Cards Are the Trojan Horse of Crypto Adoption
What makes this particularly fascinating is how it addresses the elephant in the room: adoption. For years, crypto enthusiasts have been shouting about the potential of digital assets, but the average consumer has remained skeptical. Why? Because the barrier isn’t just technical—it’s psychological. People don’t want to learn a new system; they want their money to work seamlessly within the systems they already trust. A debit card does exactly that. It’s like giving digital assets a passport to the real world.
Personally, I think this is where the crypto industry has been missing the mark. We’ve been so focused on decentralization and blockchain purity that we’ve forgotten the end user. A linked debit card isn’t just a tool; it’s a bridge. It converts the abstract into the tangible, the unfamiliar into the everyday. And that’s where the magic happens.
Trust: The Unspoken Currency
One thing that immediately stands out from the report is the role of trust. Seventy-seven percent of consumers would open a crypto wallet through their existing bank or FinTech app. What this really suggests is that trust isn’t just about security—it’s about familiarity. Banks and FinTechs already hold the keys to our financial lives. By integrating digital assets into their platforms, they’re not just offering a service; they’re legitimizing an entire industry.
What many people don’t realize is that this isn’t just a win for consumers—it’s a win for banks too. By embracing digital assets, traditional financial institutions can stay relevant in a rapidly changing landscape. It’s a symbiotic relationship: banks provide the trust, and crypto provides the innovation.
The $18 Billion Question: Where Is This Headed?
The numbers don’t lie. Monthly crypto card spending grew 15-fold from 2023 to 2025, hitting an annualized rate of $18 billion. That’s not pocket change—it’s a signal. But here’s the kicker: this isn’t just about retail spending. Stablecoins are making inroads in cross-border business payments, where their speed and cost-efficiency are solving real-world problems.
From my perspective, this is where the real opportunity lies. While consumer adoption is important, the B2B space could be the sleeper hit of the stablecoin story. Faster settlements, lower costs, and dollar-denominated value? That’s not just a nice-to-have—it’s a game-changer for global trade.
The Barriers: Why We’re Not There Yet
Of course, it’s not all smooth sailing. Limited merchant acceptance, transaction costs, volatility, and fraud concerns are still major hurdles. But here’s the thing: these aren’t insurmountable problems. They’re growing pains. Every new technology faces resistance, and digital assets are no exception.
What’s interesting is how the solutions are already emerging. Linked cards, real-time conversion, and modern issuer processing are all steps in the right direction. They’re not reinventing the wheel—they’re refining it. And that’s exactly what’s needed to bring digital assets into the mainstream.
The Bigger Picture: What This Means for the Future of Money
If you ask me, this isn’t just about payments. It’s about the evolution of money itself. Stablecoins linked to debit cards aren’t a niche product—they’re a glimpse into a future where digital and traditional currencies coexist seamlessly. This raises a deeper question: What happens when money becomes borderless, instantaneous, and universally accessible?
In my opinion, we’re not just talking about a new payment method; we’re talking about a new financial paradigm. One where the lines between fiat and digital, local and global, are blurred beyond recognition. And that’s not just exciting—it’s revolutionary.
Final Thoughts: The Debit Card as a Catalyst
The debit card might seem like a small piece of plastic, but in the context of digital assets, it’s a catalyst for change. It’s the tool that could finally bridge the gap between crypto enthusiasts and the average consumer. It’s the key to unlocking a trillion-dollar market.
Personally, I think we’re only scratching the surface of what’s possible. As more banks, FinTechs, and merchants get on board, the potential for stablecoins—and digital assets as a whole—becomes limitless. So, the next time you swipe your debit card, remember: it’s not just a transaction. It’s a glimpse into the future of money.